Are you a savvy investor looking to expand your portfolio? Wondering what the best way is to invest in gold? You’re not alone.
Gold’s reputation as an inflation hedge has made it a common holding in many portfolios. This guide compares the two main ways to own it, physical gold or a gold IRA, and what to weigh before you choose either.
Before we begin, it may help to have a high level understanding of the differences between a gold IRA vs physical gold.
When considering a gold IRA vs physical gold, it’s important to note that you hold physical gold in a gold IRA — you just do so with special benefits. In brief:
A gold IRA comes with the tax-deductible or tax-deferred benefits of a standard retirement account. Gold held in a gold IRA is not subject to the collectibles capital gains rate that applies to physical gold, but withdrawals from a traditional IRA are taxed as ordinary income. You are required to appoint a custodian for the storage of your gold in a gold IRA, who also acts on your behalf to handle all reporting requirements and disbursements.
Now that we have an overview of the differences, let’s dive into more detail to everything you need to know about how to get started with both physical gold and retirement plans backed by precious metals!
Gold IRA vs Physical Gold
Weighing the pros and cons of owning gold is worth your time — after all, you’re deciding whether it’s in your physical possession or part of a retirement portfolio.
The contrast between physical gold versus a gold IRA might seem confusing at first glance, but just understand that when you set up a gold IRA, you are purchasing physical gold and holding it in storage. They’re two sides of the same coin, so to speak. There are just some subtle differences that you need to keep in mind when deciding which is right for you.
Before we dive into each in more detail, let’s take a look at a top-level comparison between gold IRAs and physical gold.
Gold IRA vs. Physical Gold Comparison
| Gold IRA | Physical gold | |
|---|---|---|
| Holding strategy | Suited to long-term holding. Withdrawals before age 59½ generally owe a 10% additional tax unless an exception applies. | You can sell at any time. |
| Options | Only gold bars and coins that meet IRS fineness rules (99.5% for gold), plus American Gold Eagles, qualify. Silver, platinum and palladium can also be held. | You can buy gold in any form, including collector coins and jewelry. |
| Taxes | Gains are not taxed while they stay in the account. Traditional IRA withdrawals are taxed as ordinary income; qualified Roth withdrawals are tax-free. | Gold is a collectible for tax purposes. Long-term gains (held over one year) are taxed at up to 28%, short-term gains at ordinary income rates, in the year you sell. |
| Storage and security | The IRA custodian must hold the metals, usually at a depository. You cannot keep IRA gold at home. | You arrange and pay for secure storage and insurance yourself, and you can reach your gold whenever you want. |
| Fees | Custodian setup and annual fees plus depository storage fees, on top of the dealer markup. | No account fees, but you pay the dealer markup plus shipping, insurance and any storage. Selling means finding a reputable buyer. |
Gold IRA
Traditional IRAs can be a bit boring, only allowing you to invest in stocks, mutual funds, and other conventional investments. But with a self-directed IRA, you can purchase gold or other precious metals like silver, platinum, or palladium in the form of bars or coins.
A gold IRA works just like a standard IRA with the same contribution limits and distribution rules. But instead of holding boring paper assets like stocks and bonds, you can hold actual physical bullion. You own a tangible asset, though its price can fall as well as rise.
Let’s break down everything you need to know about gold IRAs.
What You Must Know About Gold IRAs
Here are a few things to know before investing in gold IRAs:
- They Can Hold A Variety of Assets. Along with gold, gold IRAs can hold precious metals, such as silver, platinum and palladium.
- They Offer Tax Benefits. Gold IRAs provide tax benefits just like traditional and Roth IRAs, allowing investors to defer taxes on their income until withdrawal, and follow the same distribution rules.
- There Are Contribution Limits. In self-directed gold IRAs, contribution limits are similar to standard IRA. For 2026, the IRS limit across all your traditional and Roth IRAs is $7,500, or $8,600 if you are 50 or older, or your taxable compensation for the year if that is less.
- There Are Fees for Setup. Gold IRAs come with additional fees for shipping, storage, and potential brokerage fees, in addition to typical startup and transaction fees of all IRAs.
- You Must Go Through a Custodian. A gold IRA requires a custodian to handle funds, disbursements, and compliance. IRS guidelines mandate an approved depository as well. Your precious metals can’t be self-stored.
- Gold Must Meet IRS Requirements. Gold IRAs have IRS-approved precious metal requirements, including gold, silver, platinum, and palladium, meeting minimum fineness. Only government mints or accredited manufacturers’ products are IRA-eligible.
- It’s Important to Research the Price of Gold. Gold IRA ownership allows investors to choose assets and determine when to purchase, providing control over portfolio management. Therefore, it’s important to do your research on the market or find a trustworthy advisor.
- You Need a Gold Distributor. When adding physical gold to a gold IRA, a distributor of precious metals must help your custodian acquire the gold products.
- You Need to Consider it a Long-Term Strategy. Physical gold within a gold IRA must adhere to distribution timing rules similar to Traditional and Roth IRAs. Gold IRAs should be considered part of long-term financial strategies due to these regulations.
- There Are Multiple Types of Gold IRAs. Gold IRAs come in different formats, including Traditional, Roth, and SEP, with different tax treatments for contributions and withdrawals. In a SEP IRA, the employer makes the contributions, up to the lesser of 25% of the employee’s pay or an annual dollar cap ($72,000 for 2026).
Who Should Invest in a Gold IRA?
Before jumping into a gold IRA, it’s important to consider your goals and risk tolerance.
Are you looking to diversify your portfolio, protect against inflation, or minimize taxes?
Keep in mind that gold can be a volatile investment, so it may not be suitable for those seeking stable returns. A gold IRA is more often used by investors who already have a diversified retirement portfolio and want a small holding in metals.
Investing in a gold IRA might be a suitable option for you if you:
- Wish to diversify your portfolio with precious metals
- Are a gold investor who plans to hold your gold for an extended period and are willing to pay fees for the added security and tax benefits that an IRA structure gives you
- Want to leverage the tax benefits that an IRA provides while protecting against inflation
Pros and Cons of Gold IRAs
| Pros | Cons |
|---|---|
| The same tax treatment as other IRAs: traditional contributions may be deductible, and qualified Roth withdrawals are tax-free. | Gold pays no interest or dividends, so returns depend only on price changes. |
| Suits a long-term buy-and-hold approach. | You cannot store the metals yourself. A custodian must hold them, usually at a depository, and you pay for it. |
| Self-directed: you choose which IRA-eligible metals to buy. | Rules apply: metals you already own generally cannot be moved into the IRA, and withdrawals before age 59½ may owe a 10% additional tax. |
| A self-directed IRA can also hold other alternative assets, such as real estate. | Custodian and storage fees usually cost more than a home safe or a bank box. |
| Gains inside the IRA are not taxed at the 28% collectibles rate. Traditional IRA withdrawals are taxed as ordinary income instead. | Selling takes longer, because the custodian has to arrange the sale or distribution. |
| The custodian keeps the records and handles IRS reporting for the account. |
Tax Benefits and Reporting Requirements for Gold IRAs
Tax Deferral
With a traditional gold IRA, contributions may be tax-deductible, depending on your income and whether you have a workplace plan. Your account grows tax-deferred, and you pay income tax on what you withdraw. With a Roth gold IRA, contributions are not deductible, but qualified withdrawals are tax-free.
No Capital Gains Tax
Buying and selling metals inside a gold IRA does not trigger capital gains tax. Tax applies when you take money or metal out. Withdrawals from a traditional IRA are taxed as ordinary income, and withdrawals before age 59½ usually also carry a 10% additional tax unless an exception applies. Roth withdrawals are tax-free once you are 59½ and the account has been open at least five years.
Reporting Requirements
Your custodian reports your contributions and the account’s year-end value to the IRS on Form 5498, and any distributions on Form 1099-R, with copies to you. You report taxable distributions on your Form 1040. If you make nondeductible contributions to a traditional IRA or take a Roth distribution, you may also need Form 8606. Speak to your tax accountant for advice.
Risks Involved in Gold IRAs
Gold held in an IRA doesn’t pay dividends, has no revenue, and must be stored in a specific institution. It should be thought of as a diversification play.
Despite its ups and downs, gold does well in times of financial instability. But if we look at history, a portfolio that just bought into the US stock market would have done better than one with gold between 1980 and 2022.
The biggest risk is that you won’t get the same gains as elsewhere. Many investors hold gold to hedge against inflation and market falls, but gold has also had long periods of falling prices. It’s up to you to weigh the pros and cons.
How to Purchase Physical Gold for an IRA
Here are the steps to purchase physical gold for an IRA:
- Open a self-directed IRA with a custodian that allows for precious metal investments.
- Select a precious metals dealer to make the actual gold purchases for your IRA.
- Fund the account with a contribution, transfer, or rollover from a qualified plan.
- Select investments for the account and have your custodian and metals dealer complete the transactions.
- Make sure the physical metals meet IRS “fineness” standards and are stored in an insured IRS-approved depository.
Note that when it comes to coins, you are limited to bullion coins issued by certain government mints.
Remember to check with your custodian to see if physical gold is one of their offerings before opening an account. You can set up the self-directed IRA as either a traditional IRA or a Roth IRA.
Physical Gold
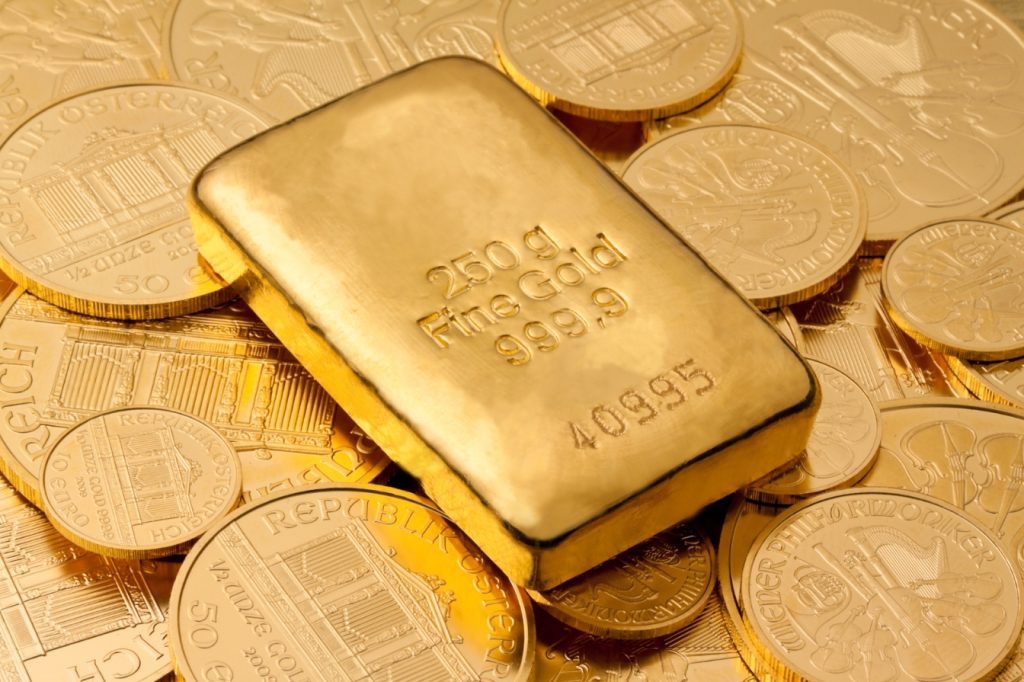
Buying physical gold can be a great way to diversify your investment portfolio. Unlike stocks and bonds, gold is a tangible asset that can be held in your hand.
However, it’s important to do your research and buy from a reputable dealer. You’ll also need to consider storage and insurance costs. While gold prices can fluctuate, it can provide a hedge against inflation and economic instability. Just remember that buying physical gold is not a guaranteed path to profits, and you’ll need to have a long-term perspective when investing in this precious metal.
Let’s break down everything you need to know about buying physical gold.
What You Must Know About Physical Gold
Here are a few things to know before investing in physical gold:
- You Must Take Full Control and Responsibility. Want to invest in gold? Take full control and responsibility. Buy, hold, and store the gold securely, and insure it. You’re also in charge of selling it when the time comes.
- You Have to Do Your Research. Make sure you research and choose a reputable dealer when buying gold. Learn where and how to sell your gold when you’re ready, and be aware of taxes and IRS rules. Remember that the purity of the gold affects its market price, so pay attention to the gold fineness.
- You Must Become an Astute Trader. Learn about gold prices and understand that selling gold doesn’t always guarantee profit. Know where and how to sell it at the right time to maximize returns.
- There Are Fees for Shipping and Handling. You’ll need to pay fees when buying and selling gold so be sure to factor this in. Educate yourself on the spread price of gold as well.
Who Should Invest in Physical Gold?
On the other hand, owning gold is still a pretty solid option. It is considered a safe haven that many investors include in their portfolios to make them more extensive. It has often held its value during periods of economic turbulence, but its price can change a lot over time, so it is not a substitute for an emergency or retirement cash fund. Gold also pays no income.
Investing in physical gold might be a suitable option for you if you:
- Prefer having a say in the specific types of gold you invest in
- Want complete control over your gold, including the option to store it at home or in a bank’s safe deposit box
- Don’t want to be bound by the rules of an IRA
- Wish to avoid paying custodian fees
- Don’t necessarily want to hold your gold for the long term, or want the option to sell at will
Pros and Cons of Physical Gold
| Pros | Cons |
|---|---|
| If stored at home or nearby, you can reach your gold quickly. | You are responsible for secure storage and insurance. |
| No custodian or account fees. | Selling means finding a reputable buyer and paying for shipping and insurance. |
| You can buy many forms of gold, at a range of prices. | Gold is a collectible for tax purposes: long-term gains are taxed at up to 28%, and gains are reported for the year you sell. |
| You can sell at any time, with no distribution rules or early withdrawal tax. | No tax deferral, unlike gold held in an IRA. |
Tax Implications and Reporting Requirements for Physical Gold
Subject to Capital Gains Tax
Gold is considered a collectible and is subject to capital gains tax by the IRS:
- If sold within a year of purchase, short-term gains are taxed at typical income rates.
- Long-term gains are taxed up to 28% depending on your tax bracket.
- You owe tax only when you sell at a gain, and you report the sale on your tax return for that year. If you held the gold for more than one year, the gain is a long-term gain taxed at the collectibles rate of up to 28%. A loss on gold held as an investment can offset other capital gains.
Reporting Requirements
To sell gold legally, you must adhere to the IRS’s reporting rules. If you invest in physical gold, you’re responsible for following these regulations. You should learn about them and know which types of gold require immediate reporting and which ones require tax filing. All tax liabilities from gold sales must be paid at the time you file your taxes for that year.
Risks of Investing in Physical Gold
As with any investment, there are a number of risks associated with investing in physical gold. These include:
- Storage and Cost. Gold can be pricey and storing it comes with extra fees. Keeping it at home or in a bank could add on to the expenses, plus you have to pay for shipping and insurance. And let’s not forget about the risk of theft!
- Purity. When buying gold, it’s important to be aware of the purity of the gold. This can be a concern, especially when dealing with older gold pieces. To avoid any issues, it’s best to buy from a reputable provider that guarantees high-quality gold products.
- Lack of Interest. Gold doesn’t generate interest or any return while in your possession, unlike many other financial products . While not really a risk, it’s more of a caution.
- Missing Out on Returns. Investing in gold coins may not always yield substantial profits when compared to other investment avenues. It should be considered a diversification play.
How to Invest in Gold
Gold is a popular choice for protecting money from inflation. You can purchase it in various ways:
- Gold Bullion. Buy genuine gold from reputable dealers including coins, bars or ingots. This is the only one of these options in which you own the metal itself.
- Gold Futures. Futures let traders bet on gold price moves with borrowed exposure (leverage), so losses can exceed the money put up. You don’t own any physical gold.
- ETFs. Buy gold through ETFs on the stock market. These investments track gold value changes, and eliminate storage issues such as insurance and fees. However, like gold futures, you are buying paper gold and not a physical asset.
Frequently Asked Questions About Gold IRAs and Physical Gold
Are gold IRAs worth it?
Gold IRAs can be a good option for investors looking to diversify their retirement portfolio and protect against inflation. Physical gold held in an IRA provides some protection against stock market volatility and is seen as a hedge against inflation. However, it’s important to note that gold does not pay any dividends or interest, and it has limited liquidity since it cannot be sold quickly for cash like stocks or other investments. Additionally, gold IRAs come with higher fees than traditional or Roth IRAs which invest solely in stocks, bonds, and mutual funds. Therefore, while gold IRAs can offer some degree of protection from inflation and stock market volatility, they may not be the best option for everyone depending on their individual financial circumstances.
Can physical gold be held in an IRA?
Yes, physical gold can be held in an IRA. An individual retirement account (IRA) is an account that allows individuals to save for retirement with special tax benefits. A gold IRA is a type of self-directed IRA that specifically allows people to invest in gold bullion. By investing in physical gold within an IRA, individuals can benefit from its long term value while also taking advantage of the tax benefits offered by IRAs.
What are the advantages of a gold IRA?
A gold IRA offers a number of advantages. For example, it allows individuals to diversify their portfolios and gain exposure to the precious metals market. Additionally, many gold IRAs offer greater control than traditional IRAs, as investors have the option to choose which specific types of investments they’d like to make with their contributions. Finally, there are some tax benefits associated with gold IRAs; for example, contributions made to a traditional self-directed IRA may be tax-deductible, depending on your income and whether you have a workplace plan. Gold IRAs also offer potential protection from inflation, as gold prices tend to rise in times of economic uncertainty.
Who holds the gold in a gold IRA?
In a gold IRA, the gold is held in custody by an IRS-approved custodian. This custodian is responsible for overseeing the account, ensuring all transactions are legitimate and within IRS regulations, and safekeeping the gold that is held in the account. The custodian must also provide reports to both the IRA owner and IRS regarding annual ownership of assets kept in the gold IRA.
Parting Words
Gold IRAs and physical gold can suit investors looking to diversify their portfolio or hedge against the volatility of financial markets. While a precious metals IRA is typically set up by a custodian and held at a secure storage facility, physical gold requires an investor to understand how to store it securely until it’s time to sell. Both gold IRAs and physical gold have risks and rewards that investors should thoroughly research before deciding which option is right for them.
Regardless if you’re interested in investing in a gold IRA or physical gold, the decision should be made with care and research in order to fully understand the risks associated with each option.
We hope this guide has been helpful in understanding the differences between gold IRAs versus physical gold investments. If you have any other questions regarding this topic please feel free to leave us a comment!
P.S. Like this article? You may also enjoy these other articles in the series:
- How to Convert Your 401k to a Gold IRA
- IRA Eligible Gold Coins
- Best Countries for Offshore Gold Storage
- Gold Bullion vs Numismatic Coins
- Cheapest Countries to Buy Gold
- Smart Tips for Investing in Gold
- Reasons to Invest in Gold
- Gold Backed IRA Account
- Home Storage Gold IRA
- Augusta Precious Metals Gold IRA Review
Correction, 16 October 2026: An earlier version of this article said that once you turn 59 you can sell gold IRA assets without paying any tax, and listed the wrong tax forms. Withdrawals from a traditional IRA are taxed as ordinary income, the age for avoiding the early withdrawal tax is 59½, and IRA owners do not file Form 1099-B for their account. We have corrected it.